The Energy Crisis Is More Severe Than You Think
The Energy Crisis Is More Severe Than You Think


Lead: The Strait of Hormuz is not an ordinary waterway—it is one of the most critical chokepoints in the global energy system. It handles approximately 20% of global oil supply and about 20% of liquefied natural gas (LNG) shipments daily. If it remains blocked for an extended period, the impact will extend far beyond oil price volatility, cascading into shipping, insurance, industrial production, food prices, and global economic growth.
The core message of this piece is that the strait does not need to be fully "closed" for a real supply disruption to occur. As long as risk perception rises, insurance coverage is withdrawn, and shipowners refuse to transit, a de facto closure can trigger actual market paralysis. While military forces may escort a few vessels, they cannot instantly restore market confidence, insurance underwriting, or commercial decision-making chains.
If hostilities escalate further and spill over into the region’s energy infrastructure, the world could face an energy shock more severe than the 1970s oil crisis. The real issue is no longer whether the strait can reopen—but whether the global energy market can still trust it to be safe.
Below is the original text:
The current White House administration seeks to convince the public that the Strait of Hormuz can be reopened through a “simple military operation,” or that it will “spontaneously resume” operations at some undefined future date. Yet, as of now, the strait remains effectively closed.
If this state persists—especially if war expands further, with Iran destroying additional energy infrastructure in the region, and the U.S. and Israel retaliating against Iranian targets—the world may be heading toward an energy crisis unseen since the 1970s, possibly even worse.
The key point is that the Strait of Hormuz does not need to be literally “fully sealed” for global supply chains to collapse. Modern energy systems are not just pipelines and tankers—they are chains of commercial decisions: shipping schedules, insurance underwriting, port access, inventory capacity.
When enough links in this chain fail, a “functionally closed” strait has the same practical effect as a total blockade.
The Strait transports roughly 20 million barrels per day of crude oil, while global daily demand stands at about 100 million barrels—meaning the strait carries around 20% of global oil supply. It also handles approximately 20% of global LNG trade. Now, very few vessels can pass through safely.
It is indeed the most vital maritime chokepoint in the global energy sector, but its impact extends far beyond energy. A vast amount of petrochemicals, aluminum, and fertilizers also traverse this route, directly affecting industrial output, food production, and food prices. Even focusing only on oil and gas, no other chokepoint is more critical to global markets.
Since the 1970s, the Gulf region has been the epicenter of global energy markets. Iraq, Saudi Arabia, the UAE, and Iran are all major oil producers. Most of this crude travels by tanker through this narrow passage to reach global markets. The Strait of Hormuz is a narrow corridor winding along Iran’s coast.
Due to this geography, disrupting shipping requires minimal cost. A few drones or a small explosive-laden boat targeting a tanker can generate significant risk. There’s no need for large-scale, prolonged military campaigns. Prior to this conflict, around 100 tankers passed through daily. Just one or two credible attacks could prompt insurers to withdraw coverage and shipping operators to deem the risk unacceptable.
Certain alternative routes exist. Saudi Arabia can export limited volumes via pipeline. Ironically, Iranian oil continues flowing. Strategic petroleum reserves have already been tapped. Sanctions on Russia and Iran have been relaxed—though the wisdom of this move remains highly debated.
Yet even accounting for all these factors, analysts estimate that up to 10 million barrels per day of oil supply remain disrupted—possibly more. That represents over 10% of global supply.
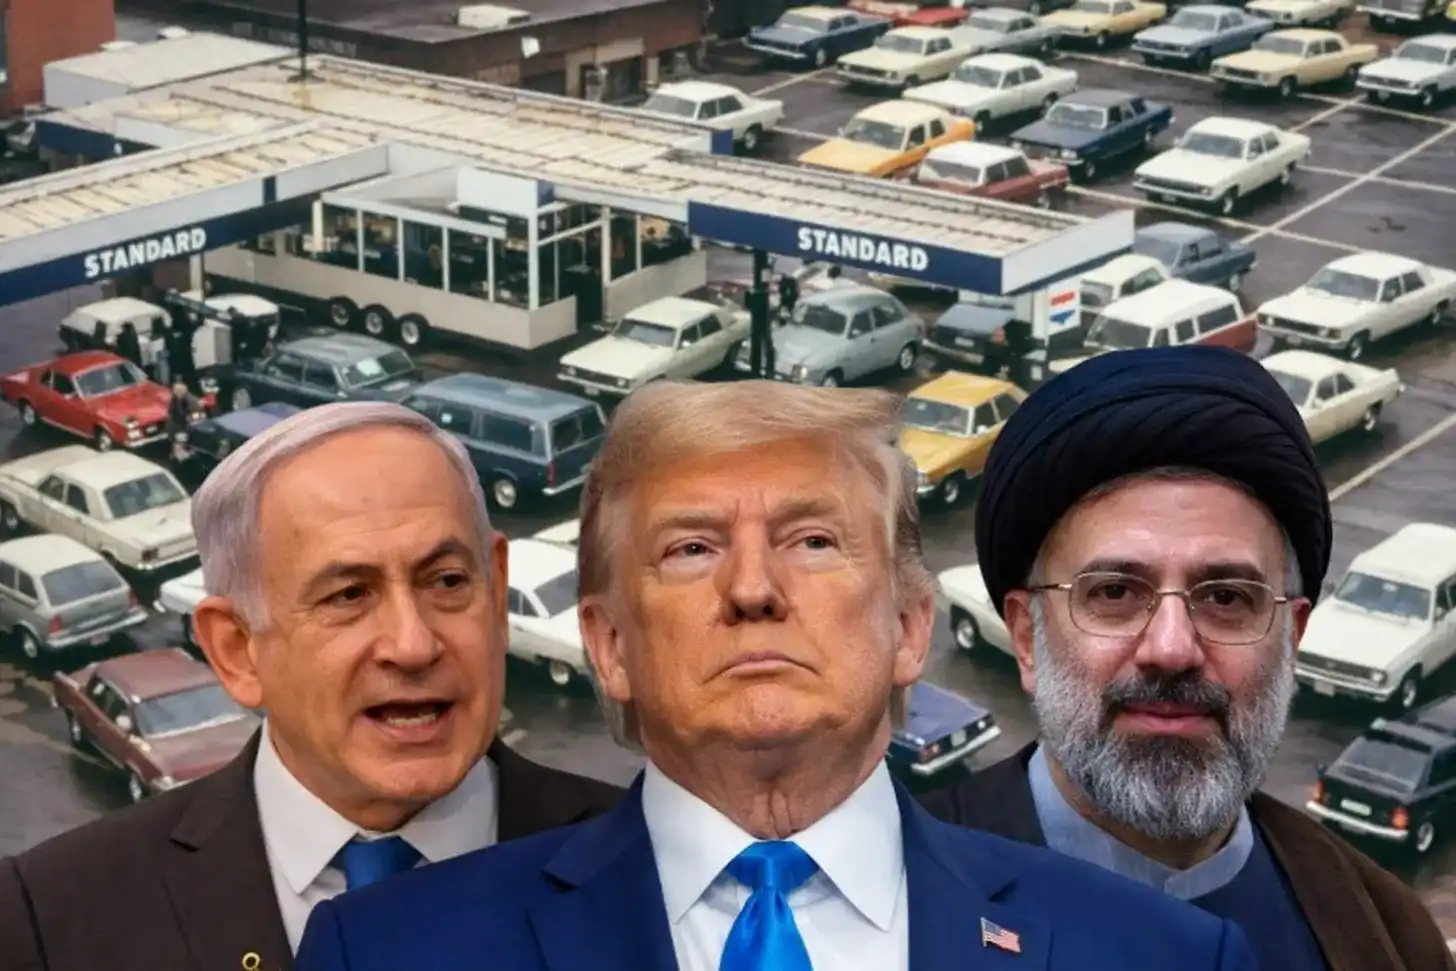
For comparison, the 1973 Arab oil embargo triggered long lines at gas stations, rationing, and severe inflation, affecting about 6% to 7% of global supply. In absolute terms and as a share of global demand, the disruption caused by a closed Strait of Hormuz would dwarf any shock modern economies have experienced.
Or put differently: why can’t the navy simply “open” the strait?
Generating risk perception requires little effort—and in global shipping, risk perception determines everything.
You don’t need to fully block the Strait or prevent every vessel from passing. You just need to hit a tanker every few days—or every couple of weeks—or even create a credible threat. This alone can cause insurers and shipping companies to conclude that the risk is no longer acceptable.
There are simply too many vessels crossing the strait to protect them all. Given modern drone technology and fast, agile boats, creating the impression that “any vessel could be attacked at any time” is not particularly difficult. Once that perception takes hold, the entire route appears unsafe.
You might protect a few warships, or escort a small number of merchant vessels under tight convoy protection. But protecting dozens of tankers and sustaining the daily flow of global energy transport is a fundamentally different problem.
And once insurance underwriting is withdrawn, the market effectively shuts down on its own.
Tankers carry high-value cargo. Operators won’t send them into high-risk zones without insurance, and insurers won’t cover open-ended geopolitical escalations. At that stage, the decision is no longer political or military—it becomes purely commercial.
Thus, even if naval escorts allow some ships to pass, they cannot resolve the underlying bottleneck. The Strait isn’t closed due to a dramatic blockade—it’s shut down because insurers pull coverage, operators refuse risk, and global commercial activity grinds to a halt.
In short, this is not merely a military issue. It’s an insurance issue, a risk management issue, and ultimately, a commercial one. And these systems react much faster than fleet deployments.
The reason the current situation feels oddly calm is partly because disruptions initially manifest as absence—not dramatic scenes. Tankers don’t burn on camera; they simply stop moving. Production declines in advance, and inventories buffer the first wave of shock.
Currently, much of the region’s energy infrastructure remains physically intact—a crucial fact. If the strait reopens quickly and infrastructure is undamaged, energy flows could normalize within weeks or months. But as risk perception solidifies and damage accumulates, this window is rapidly closing.
A closed Strait of Hormuz represents the worst-case scenario for the global energy market. If you tell people that 20 million barrels per day—most of the strait’s throughput—will be disrupted, many expect oil prices to surge to $150 or even $200 per barrel.
But what’s notable now is that prices remain only slightly above $100. Historically, this is already high—but not extreme.
Analyze the reasons behind this.
One factor is the widespread market belief that this crisis will end with leaders stepping back, declaring mission accomplished, and finding a way out. In other words, markets expect political systems won’t tolerate a prolonged, grinding conflict.
But if the situation persists, energy prices may still have a long way to go.
Today’s oil prices, as seen in newspapers, are essentially set daily by traders based on their expectations of future developments. But at some point, physical reality will prevail.
We’re already seeing early signs of this disconnect. For example, jet fuel and heating oil prices are significantly higher than what would normally be expected when benchmark crude hovers around $100 per barrel.
This indicates that physical constraints are beginning to matter.
Another reason the market appears “calm” is temporal lag. Actual supply disruptions in certain markets take time to materialize.
If a tanker loads crude in Iraq or Saudi Arabia, it may take two weeks to reach destination. We’re still consuming oil loaded before the crisis began.
So right now, the market is drawing down inventories and relying on oil already en route. But over time, physical shortages will become more apparent and acute.
When the physical reality catches up to market expectations, prices could spike sharply.
As supply disruption becomes tangible, prices must rise to a level capable of genuinely breaking demand. This is not easy. It requires massive behavioral change.
If the Strait remains closed over the coming weeks, global oil supply effectively shrinks by about 10 million barrels per day. Prices have no choice but to rise to a level sufficient to reduce global consumption by a similar amount. It’s hard to pinpoint exactly what price would achieve this—but it will certainly be far above today’s levels.
Destroying demand is not theoretical. It means consumers and businesses are forced to find alternatives—no longer buying gasoline or burning fuel.
Consumers drive less. Trips are postponed or canceled. Airlines begin adjusting flight schedules, grounding low-margin routes that are no longer financially viable at high fuel prices.
Industries follow the same logic. Factories reduce shifts, or shut down entirely. Energy-intensive facilities suspend operations because fuel costs have rendered production unprofitable.
In regions less able to bear high oil prices, we’ve already seen early versions of this response. Several Southeast Asian countries—including Thailand, Indonesia, and Malaysia—have announced emergency measures like mandatory remote work days, school closures, and other policies explicitly aimed at reducing fuel consumption.
So the question becomes: how high must oil prices rise for the global economy to cut daily consumption by around 10 million barrels?
The last time the world faced a shock of comparable scale was the 1973 Arab oil embargo. Back then, there were more easily achievable adjustments, faster efficiency gains, and quicker alternative solutions. But over the past decades, many of those adjustments have already been made.
Today, oil is used in sectors with few short-term substitutes. Long-term alternatives certainly exist—electric vehicles, electrified industrial processes, urban redesign—but in the short term, systemic flexibility is extremely scarce. The only remaining tool is blunt: compress economic activity.
People shift to public transit where possible. Businesses scale back operations. Some economic output vanishes outright.
As economist James Hamilton has shown, nearly every major oil shock in the 20th century was followed by economic recession. Whether this happens now depends on how high prices ultimately rise. But if prices must climb to a level that eliminates about 10 million barrels of global daily demand, then yes—this would be sufficient to push the global economy into recession.
The global policy toolbox contains no instrument capable of offsetting a daily loss of 10–15 million barrels of oil supply.
If the Strait of Hormuz remains closed, oil prices will inevitably surge. No combination of reserve releases, policy waivers, or short-term fixes can compensate for such a massive supply disruption.
Policymakers have already deployed some of their strongest tools. The International Energy Agency announced the largest coordinated release of strategic petroleum reserves in history—around 400 million barrels.
Notably, on the day the release was announced, oil prices rose—not fell. This wasn’t because the reserves are meaningless, but because the market recognized a mismatch in scale. Relative to the magnitude of the supply disruption, these reserves remain insufficient.
In such a crisis, what matters isn’t how many barrels are in the reserve—but how many can be delivered to the market each day. Under a scenario of losing 10–15 million barrels per day, strategic reserves might replace at most 2–3 million barrels daily—and only for a limited duration.
Beyond that, familiar ideas start resurfacing—those that appear in nearly every recent energy crisis. For instance, suspending the Jones Act to ease fuel transport between U.S. ports; relaxing environmental or fuel standards; making incremental adjustments to refinery regulations.
These measures might marginally lower gas prices by a few cents. But none can stabilize prices in the face of such a massive supply disruption.
Therefore, if the Strait of Hormuz remains closed—especially if conflict escalates into sustained physical destruction of regional energy infrastructure—the outcome is clear. This is no longer a temporary shock or a market fluctuation.
This is a full-blown energy crisis—and no policy shortcut can make it disappear.
The crucial point is that energy markets don’t just react to “war starting” or “ceasefire declared.” They respond to risk perception and physical damage—both of which can persist for months, even years, after hostilities end.
One possible outcome is that risk perception never fully dissipates. Even if the U.S. declares the operation over, Iran and Israel still have influence. Shipping will only resume when insurers, operators, and governments collectively believe passage is truly safe.
This means that even without further attacks, persistent uncertainty could keep the Strait functionally closed. Tankers won’t return simply because of a speech or a ceasefire declaration. They’ll only come back when the risk premium disappears—and that requires trust, not statements.
But the greater danger lies in physical damage.
If key export hubs or processing facilities are struck, retaliatory attacks on other critical energy assets are likely. At that stage, timelines shift from weeks to years.
We’ve seen this before. In 2019, Houthi attacks on Saudi Arabia’s Abqaiq oil processing facility temporarily halted 5.7 million barrels per day of capacity and sent oil prices soaring at record speed. Although physical damage was limited and Saudi Arabia restored output remarkably quickly, the event demonstrated how fragile the entire system is—and how much worse the consequences could have been.
If current attacks escalate further, it’s easy to imagine millions more barrels of supply going offline daily—supplies that remain untouched today.
The Strait itself has partial bypass routes, but their capacity is limited and equally vulnerable. Before the crisis, Saudi Arabia exported about 7 million barrels per day. Now, via pipelines bypassing the Strait—particularly to Red Sea ports like Yanbu—it manages exports of 4–5 million barrels per day.
But these routes are not immune to disruption. Over recent years, Houthi forces have proven they can effectively target Red Sea shipping. While we haven’t yet seen sustained attacks in this phase of conflict, the risk is clearly rising given Houthi ties to Iran.
Then there’s Qatar. After a recent attack on one of its LNG facilities, Qatari authorities stated that repairing just 20% of the damage could take three to five years—perhaps closer to two or three. Regardless, the timeline is measured in years, not weeks or months.
This is the most critical distinction.
If hostilities end cleanly and most infrastructure remains intact, energy flows could recover relatively quickly. But if key facilities across the region are damaged in escalating retaliation, high prices and supply constraints will persist long after the guns fall silent.
In that case, believing that a ceasefire will immediately restore normalcy in energy markets is a comforting illusion—one that is dangerously misleading. Unfortunately, this seems to be the illusion underpinning the current strategy.
Disclaimer: Contains third-party opinions, does not constitute financial advice
SpaceXAI to Tidy Up Subscription Chaos, Grok and Cursor to Unify Plans Within Weeks
16 days ago
JPMorgan: Oracle's Backlog Orders Up by $26 Billion, Funding Trail Raises Questions
16 days ago
The Nasdaq-100 Index futures decline widens to 1.5%
16 days agoJefferies: Expecting Fed rate hike this week, Wunsch's comments to be pivotal
16 days agoData: Bitcoin's current holding volume has decreased by 13.5% compared to September 3rd, suggesting the market may have already begun deleveraging ahead of time
16 days ago
The UK's Financial Conduct Authority is exploring regulatory exemptions for tokenized gold
16 days agoKOSPI Index drops over 3%, SK Hynix down 6.34%
16 days ago

