Pantera Capital Review: The Largest Liquidation Wave in History, Token Prices Down 60%, What Lies Ahead for the 2026 Market?
Pantera Capital Review: The Largest Liquidation Wave in History, Token Prices Down 60%, What Lies Ahead for the 2026 Market?


Market Outlook for 2026
The returns in the crypto market during 2025 were not driven by fundamentals. This was a year dominated by macro conditions, positioning, capital flows, and structural market effects—especially for assets beyond Bitcoin.
Reviewing the timeline of major macro and policy inflection points throughout the year helps explain why the market performance was so disjointed.
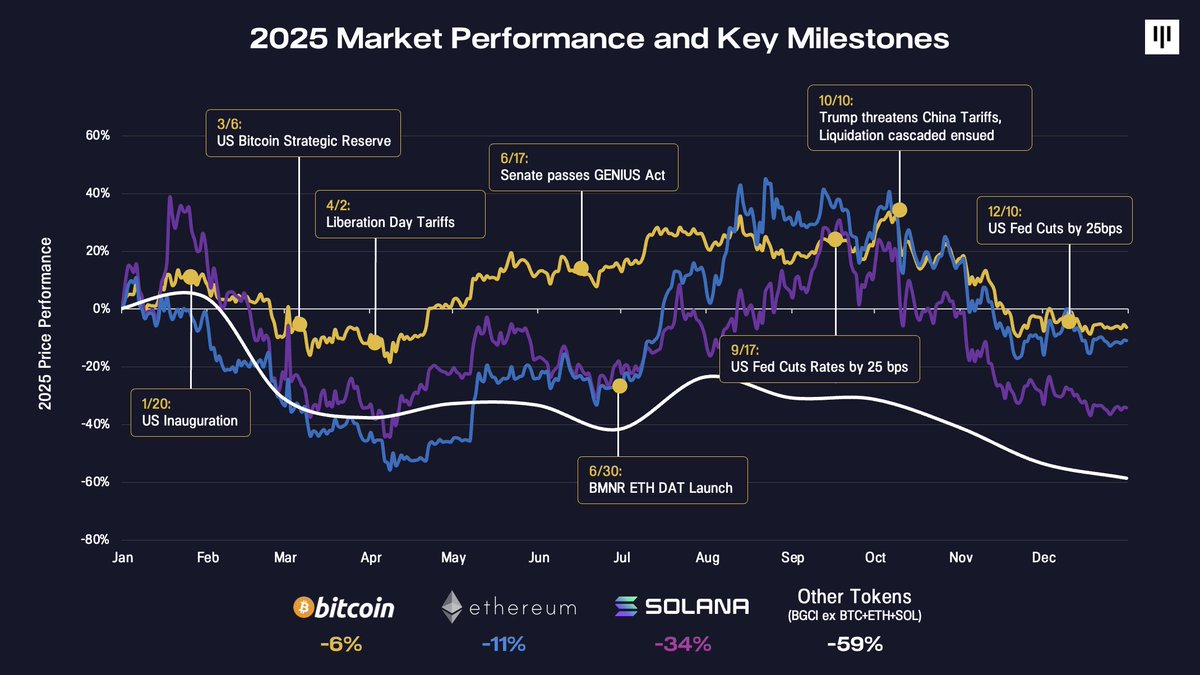
The year began with the U.S. presidential inauguration, ultimately proving to be a classic “sell-the-news” moment and an early warning sign of volatility. Subsequent months saw repeated swings in risk appetite—from optimism following the announcement of the U.S. strategic Bitcoin reserve, to renewed pressure from tariffs on “Liberation Day.” Mid-year brought constructive progress, including the passage of the GENIUS Act, the rise of digital asset treasuries (DATs) such as Bitmine Immersion, and the Federal Reserve’s start of rate cuts, which stabilized market sentiment over several months.
A decisive turning point emerged in the fourth quarter, as multiple challenges converged simultaneously. The sell-off on October 10 triggered the largest chain-wide liquidation cascade in crypto history—exceeding the scale of the Terra/Luna collapse and the FTX bankruptcy period—with over $20 billion in nominal positions wiped out. The market required time to digest this shock. Meanwhile, the key marginal buyers throughout the year (DATs) began exhausting their incremental purchasing power. This downward momentum was amplified by seasonal pressures, including tax-loss harvesting (particularly within ETFs and DATs), portfolio rebalancing, and year-end systematic CTA flows.
Bitcoin ended 2025 slightly lower, down approximately 6%. Ethereum declined by about 11%. From there, performance deteriorated sharply: Solana dropped 34%, while the broader token universe (BGCI excluding BTC, ETH, and SOL) fell nearly 60%.
This was an extremely narrow market. The divergence became even more stark when examining the return distribution across the token universe.
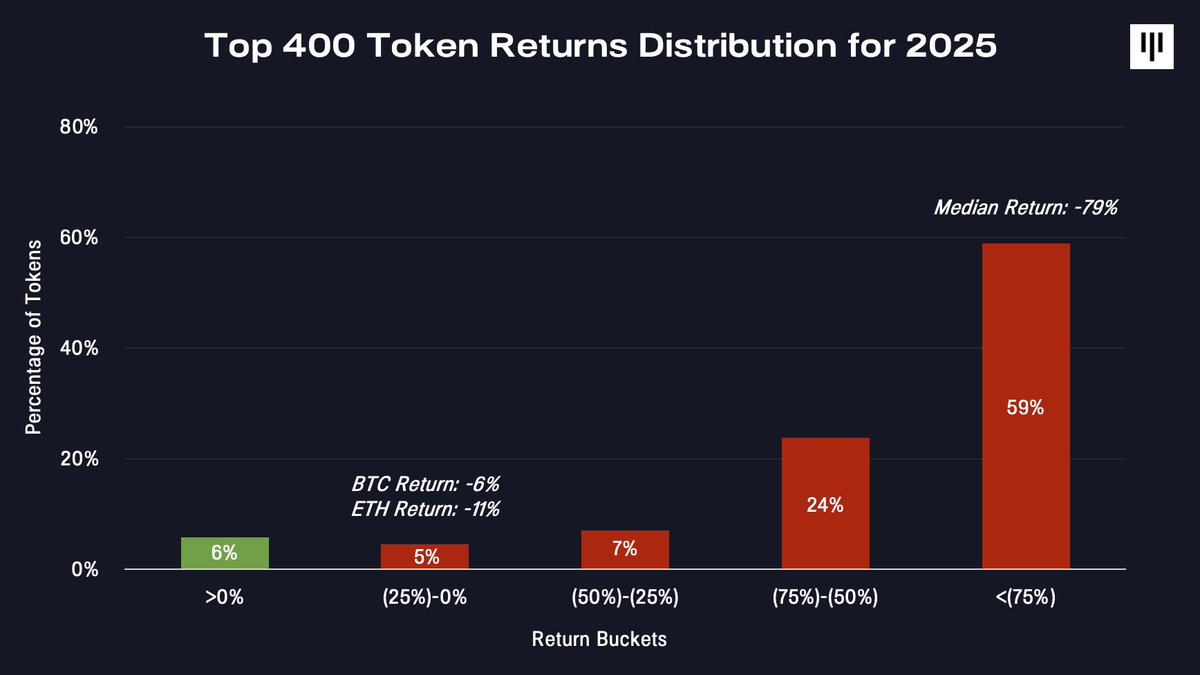
Only a small fraction of tokens generated positive returns. The vast majority experienced deep drawdowns—the median token declined by 79%.
A Year-Long Altcoin Bear Market
The most underestimated reality of 2025 may be that the non-Bitcoin token market had actually entered bear territory as early as December 2024.
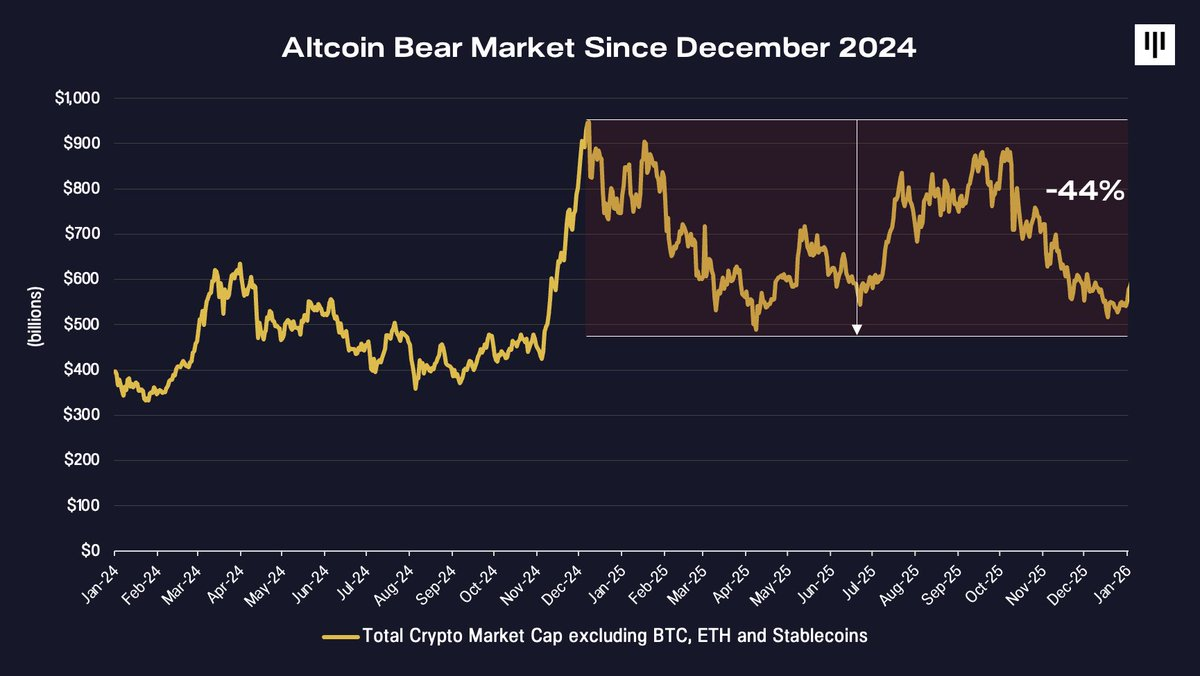
Total market cap for cryptocurrencies excluding Bitcoin, Ethereum, and stablecoins peaked at the end of 2024 and has since been in a gradual decline—down roughly 44% by the end of 2025. From this perspective, a year that looked relatively resilient for Bitcoin was merely a continuation of an unresolved bear market for the rest of the ecosystem.
Investment portfolios with significant exposure to mid- and small-cap tokens faced structural headwinds.
The widening divergence between Bitcoin and the broader token market reflects fundamental differences. Bitcoin benefits from a singular, widely understood thesis—digital gold—and increasingly from mechanical demand driven by sovereign nations, governments, ETFs, and corporate treasuries. In contrast, other tokens represent a heterogeneous set of disruptive technologies, with less standardized access, weaker institutional support, and more complex value-capture dynamics.
This divergence is clearly visible in price action.
Structural Headwinds Facing Tokens
In 2025, multiple forces intensified pressure on the broader token ecosystem.
1. Value Accumulation and Investor Rights
One of the most persistent challenges remains unresolved around value accumulation. In traditional stock markets, shareholders benefit from clear legal claims to cash flows, governance, and residual value. By contrast, tokens typically rely on protocol-level mechanisms enforced by code rather than government institutions.
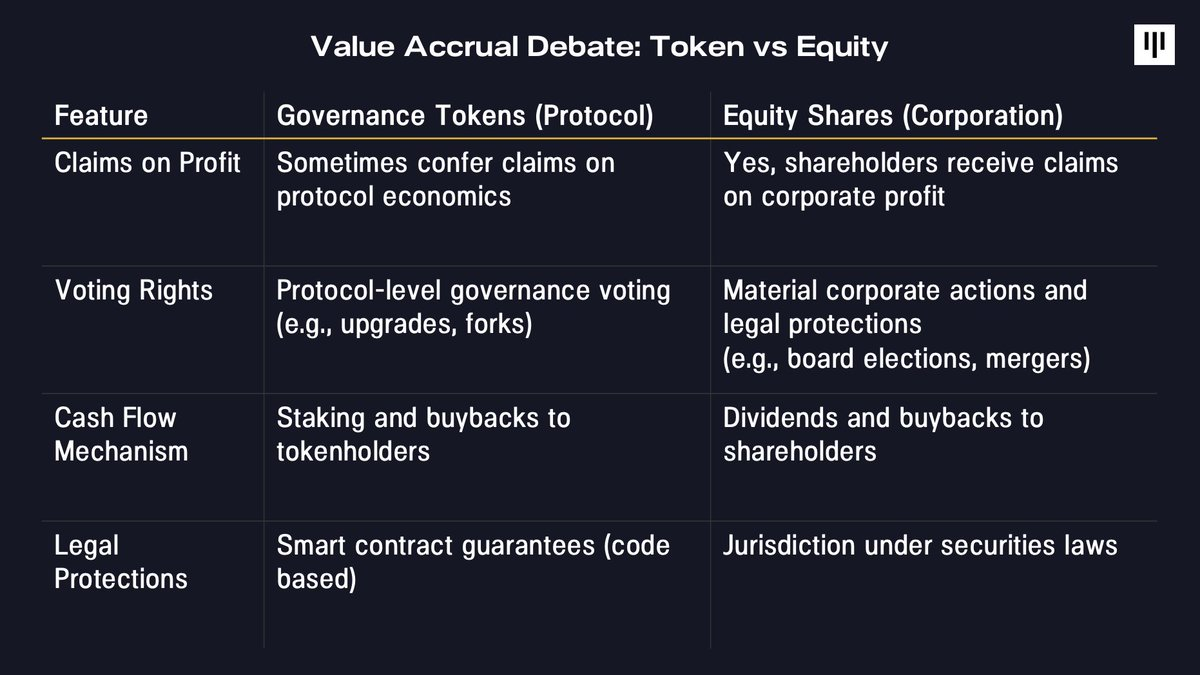
This tension came into sharp focus this year, particularly in cases where token-based ecosystems were acquired or restructured without direct compensation to token holders, including Aave, Tensor, and Axelar. These events rippled through the entire market, undermining confidence even in projects with relatively strong tokenomics.
Against this backdrop, digital asset equities outperformed tokens, benefiting from clearer value-capture pathways as investors sought defensive positions.
2. Slowing On-Chain Activity
On-chain fundamentals also weakened in the second half of the year.
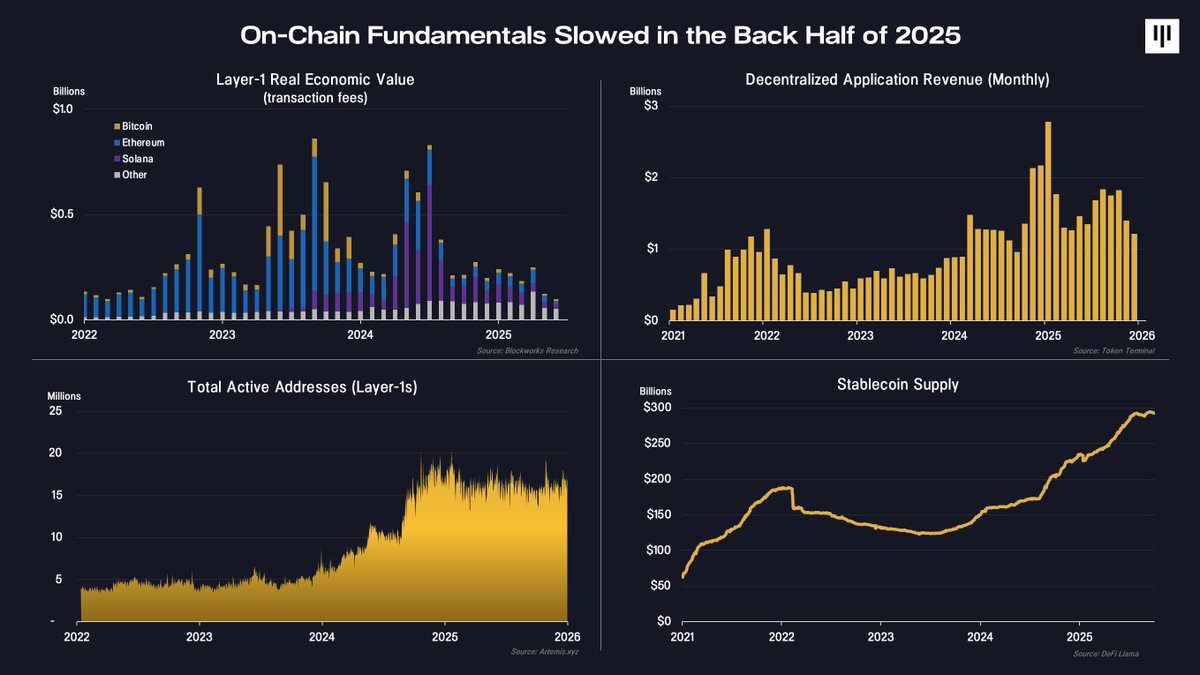
Activity slowed across key metrics—including layer-one network revenue, decentralized application fees, and active addresses. Notably, stablecoin supply continued to grow, indicating sustained adoption of blockchain for payments and settlements. However, the bulk of economic value associated with stablecoins flowed into off-chain equity-based businesses, rather than tokenized protocols.
While foundational infrastructure remained robust, marginal, procyclical activity declined. This shift was directly reflected in token price movements.
3. Rotation of Speculative Capital
Finally, capital flows reversed. Marginal capital supporting the broader token space had historically come from speculative retail investors. Although institutional adoption continued to grow, it remained largely concentrated in assets accessible via ETFs—Bitcoin, Ethereum, and Solana toward year-end.
In 2025, speculative attention shifted elsewhere.
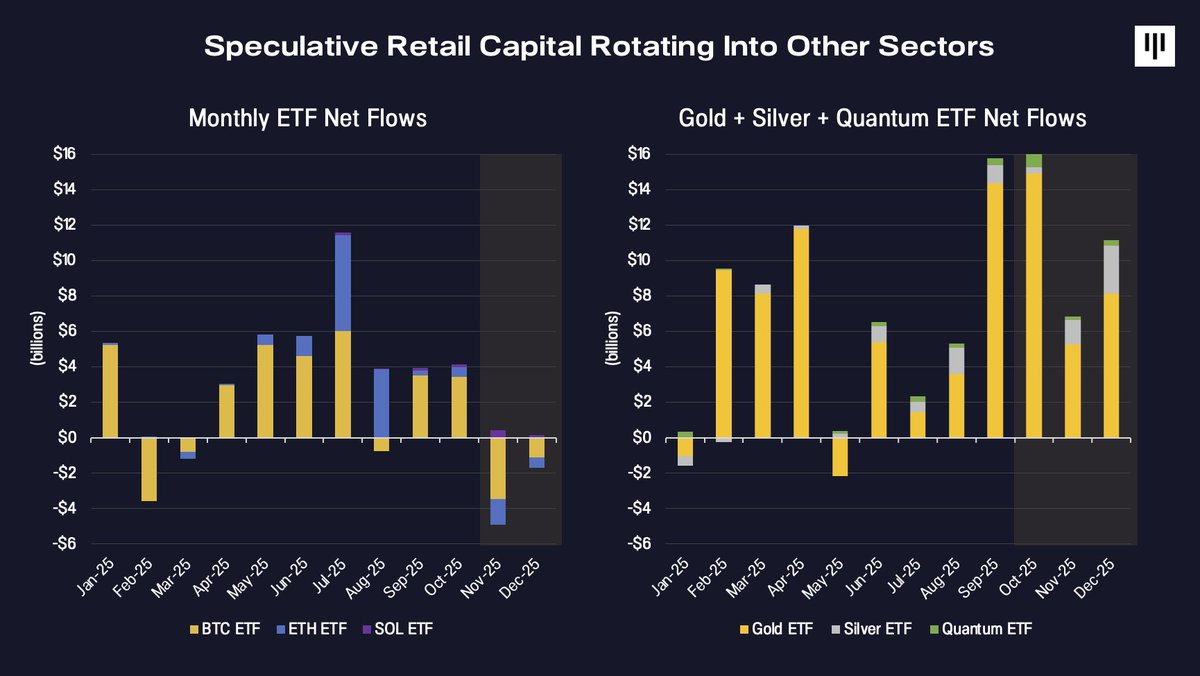
ETF inflows surged into gold, silver, and emerging thematic plays (such as quantum computing), while digital asset ETF flows slowed and turned negative by year-end. This rotation coincided precisely with the worsening breadth of tokens, reinforcing downward momentum.
Mood, Positioning, and Historical Context
By year-end, sentiment compressed to historically surrender-level extremes.
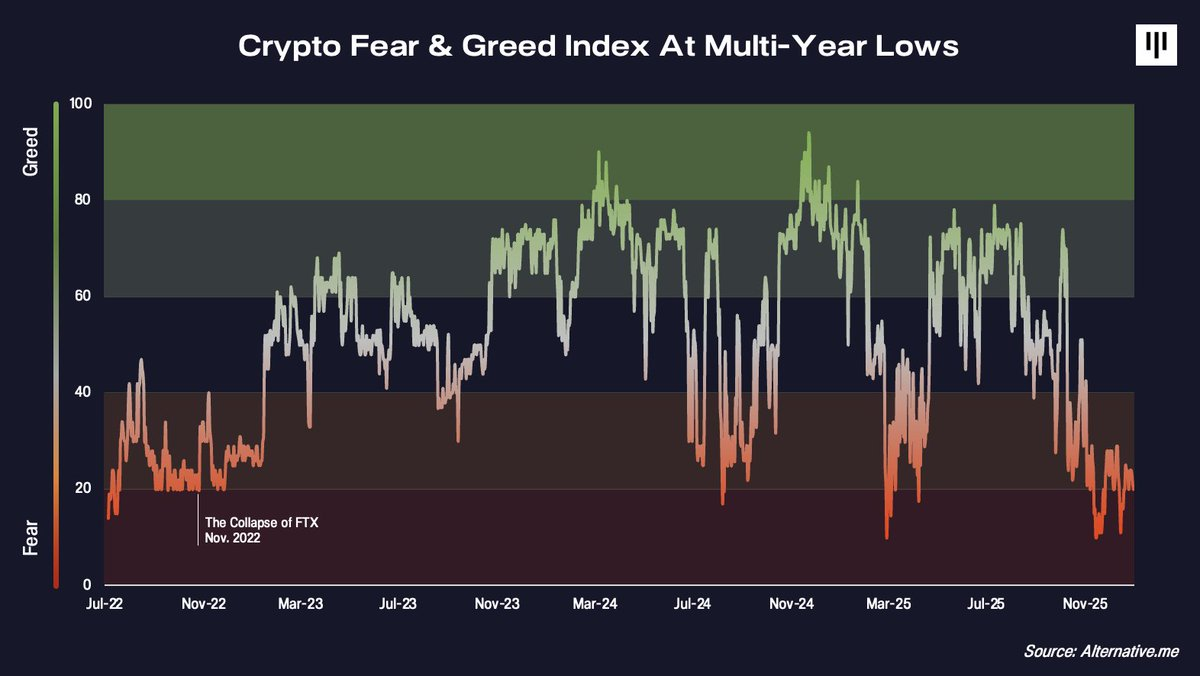
The Fear & Greed Index reached levels last seen during acute stress periods—including after the FTX collapse. At the same time, perpetual futures funding rates declined, signaling reduced leverage and diminished speculative excess.
Seasonal factors also played a role. December has historically been a weak month for Bitcoin and the broader crypto market, burdened by tax-loss selling, portfolio rebalancing, and liquidity constraints—mechanical pressures independent of fundamentals.
Importantly, from a longer-term perspective, the duration of the current non-Bitcoin drawdown closely aligns with prior cycles.
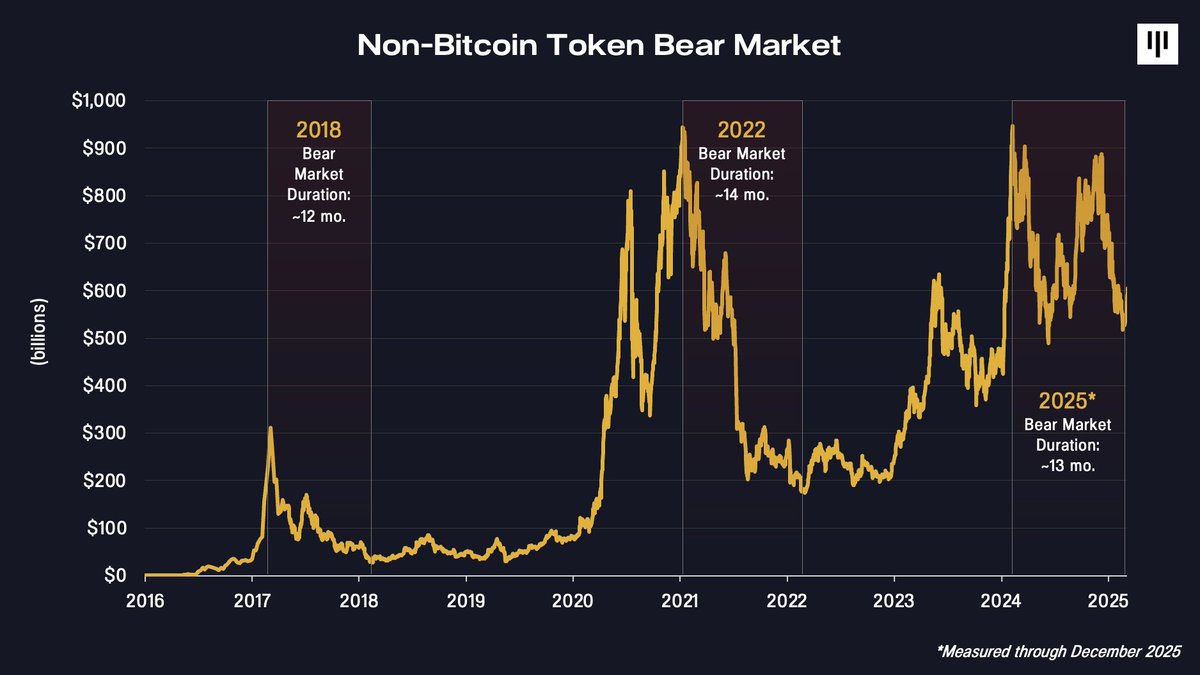
The bear markets of 2018 and 2022 lasted approximately 12 to 14 months. Calculating from the peak at the end of 2024, the current drawdown now falls within the same range. While this does not guarantee a bottom, it does indicate that substantial compression based on time and price has already occurred.
Why the Outlook Improves from Here
Despite the challenges of 2025, several compelling reasons exist to maintain constructive optimism for the future.
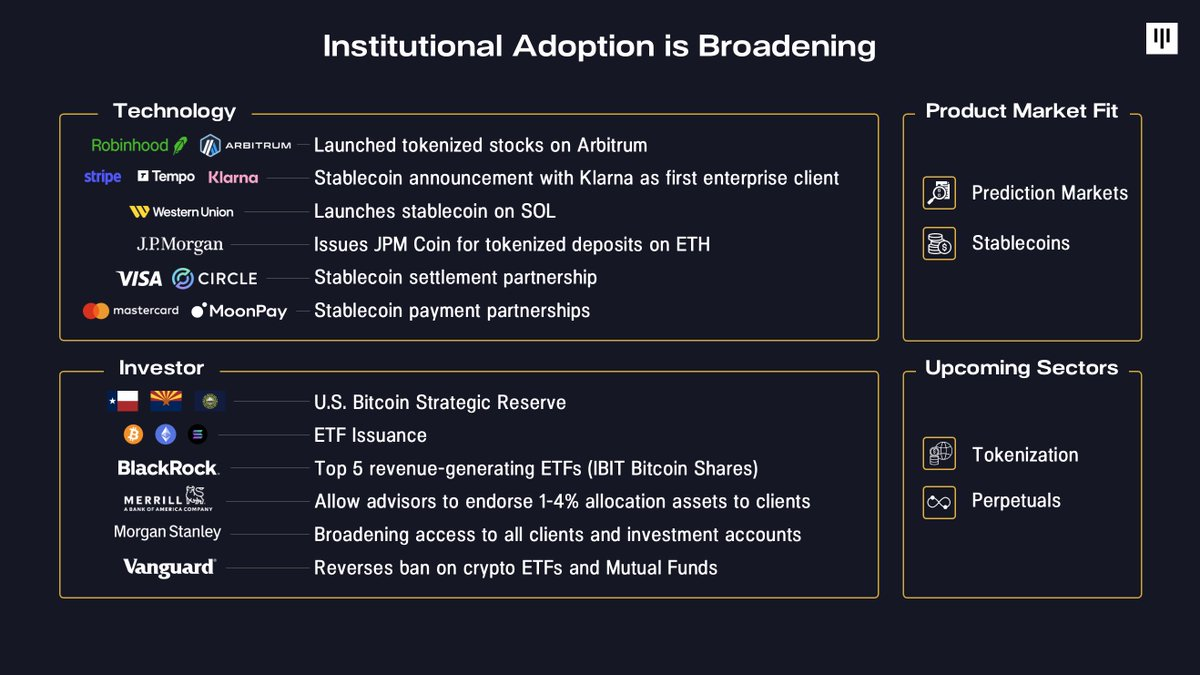
First, institutional adoption continues to expand. Enterprises are increasingly integrating blockchain into core products—from Robinhood launching tokenized stocks to Stripe developing stablecoin infrastructure, to JPMorgan tokenizing deposits. On the capital front, sovereign reserves have been established, and securities firms, retirement platforms, and large asset managers have significantly lowered entry barriers.
Second, product-market fit is becoming clearer. Stablecoins and prediction markets gained breakthrough attention and adoption in 2025 as standout use cases, while broader tokenization and perpetual futures are showing early signs of product-market fit.
Third, the macro environment is supportive. The U.S. economy has remained resilient, with wage growth outpacing inflation and corporate earnings expanding. With the Fed now halting quantitative tightening, liquidity conditions are improving. Declining long-term yields combined with accommodative monetary policy have historically been constructive for risk assets—including digital assets.
Finally, penetration remains astonishingly low. As Tom Lee of Bitmine noted: only 4.4 million addresses hold more than $10,000 worth of Bitcoin, compared to 900 million traditional investment accounts globally. According to Bank of America’s institutional investor survey, 67% of professional fund managers still have zero exposure to digital assets. Even modest shifts in allocation over time represent a significant source of latent demand.
Conclusion
2025 was a difficult year for the broader token market—characterized by extreme dispersion, stronger performance among major coins, and prolonged weakness outside Bitcoin. Yet it was also a year of advancement in institutional adoption, clearer product-market fit, and valuation compression across much of the ecosystem.
A solid fundamental backdrop following a year of bearish conditions in the wider token space may present opportunity. As sentiment clears, leverage diminishes, and major repricing occurs behind us, forward-looking positioning appears increasingly asymmetric—provided fundamentals remain stable and breadth returns. Historically, periods of chaos lay the foundation for the next phase of growth.
[1] Performance of the Bloomberg Galaxy Crypto Index (BGCI) excludes fees that would reduce performance. Any index is for reference only and serves as a general example of market performance. No index can be directly compared to Pantera Fund performance, partly because indices are not actively managed. Investment results of the Pantera Fund are not intended to predict or imply future returns of the Pantera Fund.
PANTERA REVIEW — Looking Back at 2026
Author: @JonathanGieg
As we embark on 2026, we anticipate a more electrifying year for crypto than the previous one. But before turning the page, we want to take a moment to reflect on what 2025 delivered.
2025 was a defining year for Pantera. We deployed capital at levels never seen before, led the majority of our new investments, and expanded our global footprint into industries and regions we believe will define the next decade of crypto. Meanwhile, our portfolio received strong public market validation, with four portfolio companies going public and securing major strategic acquisitions.
Read about our progress in 2025:
Nine Predictions for 2026
Author: @veradittakit
#1 Real World Assets (RWA) Take Off
By mid-December 2025, total locked value (TVL) in RWA reached $16.6 billion, accounting for approximately 14% of DeFi’s total TVL.
Prediction:
· Government bonds and private credit could at least double.
· Tokenized stocks and equity may grow faster when the SEC’s anticipated "innovation exemption" under its "crypto project" framework launches.
· An unexpected sector (carbon credits, mining rights, or energy projects) will surge. Characteristics of this space include fragmented liquidity, global distribution, and lack of standardization—areas where blockchain-based markets can help solve these issues.
#2 AI Revolutionizes On-Chain Security
AI-powered security and blockchain development tools have become incredibly powerful. Real-time fraud detection, 95% accurate Bitcoin transaction labeling, and instant smart contract debugging are now available—detecting millions of dollars in blockchain vulnerabilities.
Prediction: In 2026, imagine a larger shift toward on-chain intelligence, where deterministic, verifiable rules take over smart contract-based governance. Applications will scan code near real-time, instantly identify logical errors and exploits, and provide immediate debugging feedback. The next unicorn will be a pioneering on-chain security firm that improves security by 100x.
#3 Prediction Markets Become Acquisition Targets
Through the first ten months of 2025, $28 billion in trading volume was recorded. Prediction markets are consolidating around institutional infrastructure. The week of October 20 saw a record high of $2.3 billion in trading volume.
Prediction: The industry will see acquisitions exceeding $1 billion, excluding Polymarket or Kalshi. Winning platforms will feature built-in liquidity rails, embedded market discovery intelligence, and insights into where capital is flowing and why. Forget flashy new buttons—this is about empowering users effortlessly: instant access to hidden pools, smarter routing, and predictive order flow.
Platforms focused on sports, like DraftKings and FanDuel, have already gone mainstream, partnering with media for real-time odds distribution. New entrants targeting sports, such as NoVig, will vertically expand their presence, and new startups will emerge in Asia-Pacific—a region to watch.
#4 AI Becomes Your Personal Crypto Co-Pilot
As systems mature, consumer AI platform usage will surge, delivering hyper-personalized experiences tailored to individual expectations. Seamless integration makes advanced AI feel effortless, shifting usage from clumsy to instantaneous.
Prediction: Platforms like Surf.ai will attract users ranging from crypto-curious newcomers to active traders in 2026, thanks to intuitive advanced AI models, proprietary encrypted datasets, and multi-step workflow agents. I believe the blend of sophisticated technology and accessible design makes Surf the go-to crypto research tool, delivering market insights with four times the speed of generic alternatives in on-chain support.
#5 Banking Giants Prepare: G7-Linked Stablecoins Imminent
Ten major banks are currently in the early stages of exploring consortium stablecoin issuance pegged to G7 currencies. Financial institutions are assessing whether a standardized, compliant, risk-managed stablecoin could deliver digital currency benefits to individuals and institutions. Meanwhile, a group of ten European banks is investigating euro-pegged stablecoin issuance.
Prediction: A major banking coalition will launch its own stablecoin (whether through pilot outcomes in 2026 or different coalitions doing so).
#6 Privacy, Payments, Perpetuals: The Institutional Triad
Privacy tech is thriving in institutional use cases, with transparent-confidential combinations from protocols like Zama and Canton—though retail adoption hasn’t found traction or scalability. Stablecoins have reached $310 billion in market cap, more than doubling since 2023 and growing for 25 consecutive months. Perpetual swaps now account for about 78% of crypto derivatives volume, and the gap between perpetuals and spot options continues to widen.
Prediction: The gap between institutional and retail adoption of privacy will widen in 2026. Stablecoins will follow a long-term path toward $2 trillion+, reaching at least $500 billion next year, and perpetual contracts will maintain their momentum through 2026.
#7 Institutional Macro Perspective
As of December 15, 17.9% of BTC holdings are now held by public and private companies, ETFs, and sovereign entities.
Prediction: 2026 won’t be about hype or memes. It will be about integration, genuine compliance, and institutional capital driven by public market liquidity. Crypto will integrate into mainstream platforms, upgrade financial rails, and challenge incumbent players.
#8 The Largest Crypto IPO Year in History
There were 335 U.S. IPOs in 2025—up 55% from 2024—with many being crypto-friendly, including 9 blockchain IPOs. This includes crypto-native companies like Circle Internet Group (listed May 27, 2025) and crypto-inclusive SPACs such as Bitcoin Infrastructure Acquisition Corp (listed December 2, 2025).
Prediction: 2026 will be a bigger year for digital asset public listings. Coinbase reports that 76% of companies plan to add tokenized assets in 2026, with some aiming for over 5% of their portfolio. Morpho, as an example protocol, reached $8.6 billion in TVL in November 2025.
#9 Accelerated Integration of Digital Asset Treasuries
In 2021, fewer than 10 publicly traded companies held Bitcoin. By mid-December 2025, 151 listed companies held $95 billion, including government holdings rising to 164 entities and $148 billion.
Prediction: 2026 will bring brutal pruning. In each major asset class, only one or two players will dominate. Others will be acquired or left behind, except for one long-tail token winner that follows. The trend is also globalizing. Japan’s Metaplanet has already been aggressive, meaning the U.S. no longer monopolizes this movement as the global treasury landscape diversifies.
Wishing you all the best for 2026.
To learn more, read our Pantera Blockchain Letter.
Author: Cosmo Jiang, Translated by DeepFlow TechFlow
Disclaimer: Contains third-party opinions, does not constitute financial advice
SpaceXAI to Tidy Up Subscription Chaos, Grok and Cursor to Unify Plans Within Weeks
16 days ago
JPMorgan: Oracle's Backlog Orders Up by $26 Billion, Funding Trail Raises Questions
16 days ago
The Nasdaq-100 Index futures decline widens to 1.5%
16 days agoJefferies: Expecting Fed rate hike this week, Wunsch's comments to be pivotal
16 days agoData: Bitcoin's current holding volume has decreased by 13.5% compared to September 3rd, suggesting the market may have already begun deleveraging ahead of time
16 days ago
The UK's Financial Conduct Authority is exploring regulatory exemptions for tokenized gold
16 days agoKOSPI Index drops over 3%, SK Hynix down 6.34%
16 days ago

