Goldman Sachs Sees Promise in Crypto Brokerage Platforms: Can the Market Sustain a New Cycle?
Goldman Sachs Sees Promise in Crypto Brokerage Platforms: Can the Market Sustain a New Cycle?


Brokerage and crypto-related stocks outperformed market expectations following the second-quarter earnings season.
According to Goldman Sachs, since the first company in the sector reported Q2 results on July 21, covered companies' stock prices rose an average of 3%, outperforming the S&P 500 by about 1 percentage point. Q2 industry profitability exceeded consensus estimates by 8%, revenue by 2%, but expenses were also up 5%.
Goldman Sachs maintains a cautiously optimistic outlook for the second half. The core driver behind this view is not a revival in crypto trading, but rather structural growth potential and seasonal recovery upside in traditional brokerage operations and prediction markets. Recent upticks in crypto asset market cap have preserved additional upward potential for the sector.
Valuations also offer some margin of safety. Current sector forward-adjusted P/E ratio is around 24x, EV/EBITDA approximately 14.5x—both near the 30th percentile over the past five years. Goldman Sachs believes that if trading volumes improve starting in September, the sector still has room for re-rating.
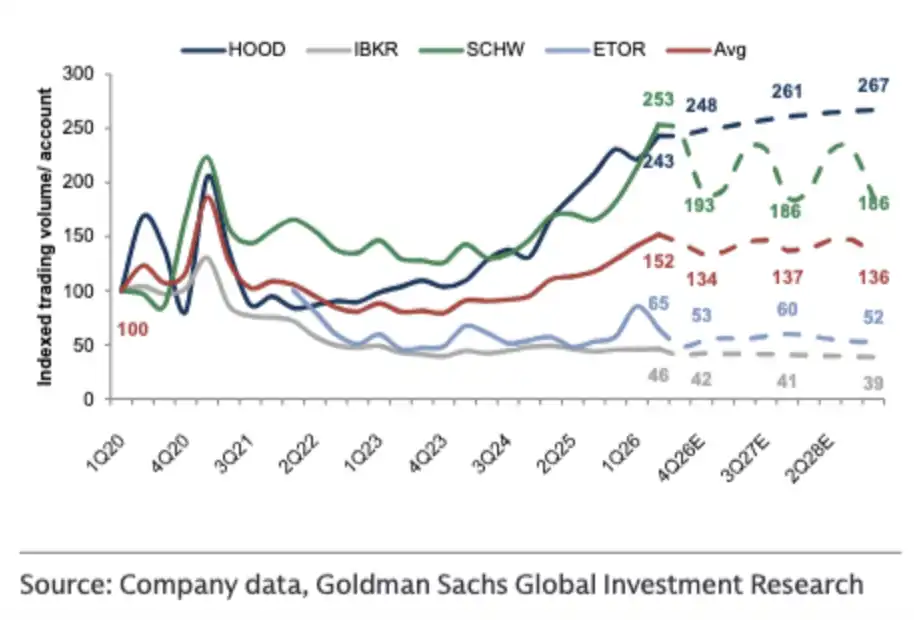
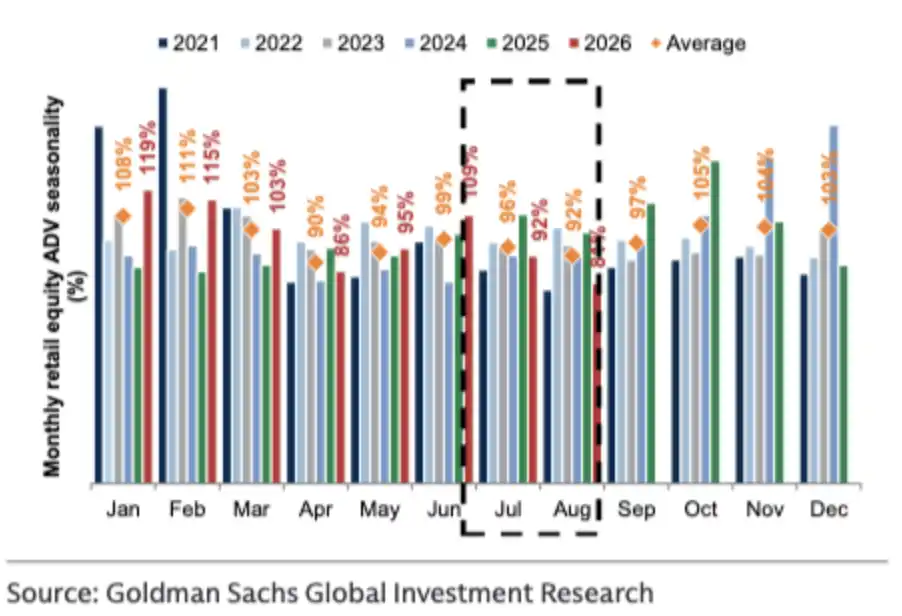
In July and August, U.S. retail equity trading volume declined sequentially by about 15% and 14%, respectively. Given that Q2 trading volume and margin balances are already 40% and 100% higher than their 2021 peaks, concerns are mounting about whether this retail trading cycle has already peaked.
Goldman Sachs’ assessment is relatively moderate. The report argues that absolute trading volume remains at record highs, partly driven by expansion in broker platform scale. From 2023 to 2025, major broker account counts grew at a compound annual rate of ~13%, while client assets increased ~40% annually. After adjusting for account growth, unit account trading volume in Q2 2026 remains ~8% below the 2021 cycle peak.
Margins follow a similar pattern. Although absolute margin balances have clearly surpassed 2021 levels, the ratio of margin balances to client assets remains below the previous peak. Given the strong historical correlation between margin balances and retail equity trading volume, Goldman Sachs concludes that this cycle still has room for further expansion, albeit with potentially slowing growth rates.
Seasonality must also be considered. July and August are typically weak months for retail trading. This year’s declines exceed historical seasonal patterns, but part of the decline may reflect early booking into June. That month saw active capital market activity, driving retail participation and trading volume to record highs.
Goldman Sachs forecasts U.S. equity issuance in 2026 will reach a record $67.5 billion, with Q2 issuance around $25.2 billion. Historical data shows that equity issuance typically lags by about one quarter before boosting retail trading, benefiting securities lending, equity trading, and IPO subscription activities.
Based on seasonal recovery and equity issuance momentum, Goldman Sachs expects traditional retail brokerage commission growth to rise ~28% YoY in Q3, with average equity and options trading volume increasing ~19%. This forecast still hinges on whether trading activity rebounds as expected in September.
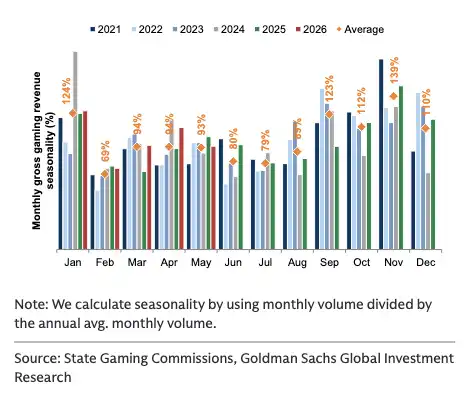
Goldman Sachs believes prediction markets simultaneously possess structural growth potential and cyclical recovery space, with fall trading rebound likely more pronounced than in traditional brokerage.
From January 2024 to July 2026, annualized trading volume in prediction markets grew cumulatively by ~1160%. Since August 2025, monthly unique users have posted sequential growth every month except April 2026, indicating continued user base expansion.
Exponential growth initially masked seasonal patterns. According to Goldman Sachs data, sports, crypto, and political contracts account for the vast majority of trading volume. In July 2026, sports contracts represented ~79% of industry volume, crypto contracts ~15%, and political contracts ~2%.
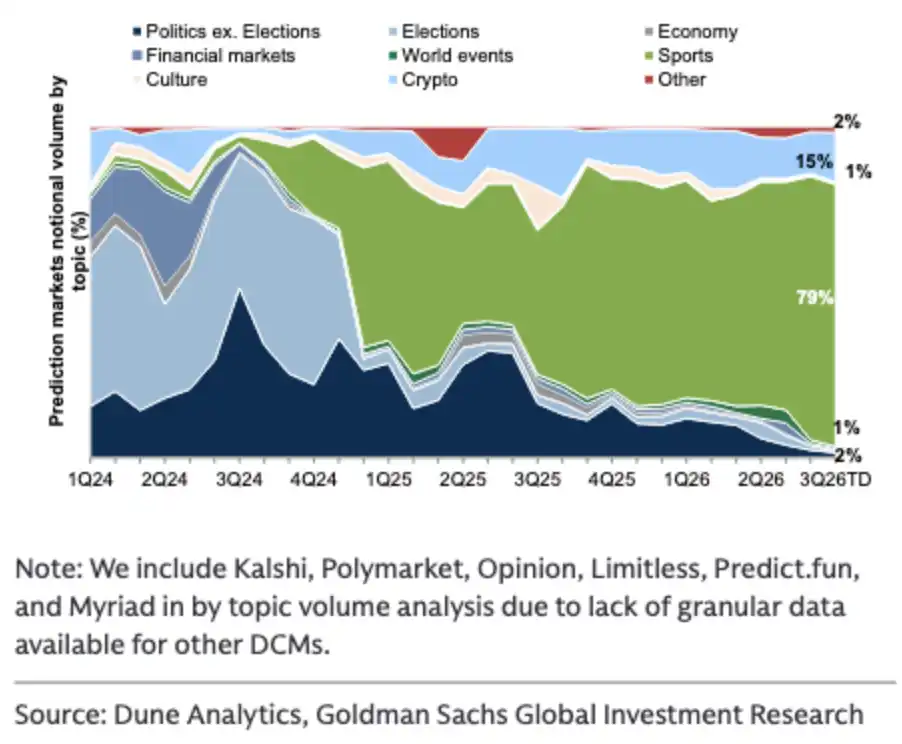
These three contract types are driven by different cycles. Sports trading typically rebounds after major U.S. professional leagues resume, with activity peaking from September to January of the following year; political contracts surge ahead of elections; crypto event contracts are influenced by coin price movements and broader crypto market cycles.
With fewer summer sports events and U.S. midterm election trading not yet at peak levels, prediction market volume declined ~15% MoM in August. Goldman Sachs attributes this primarily to seasonal dynamics in underlying event contracts, not a termination of structural growth.
Starting in September, U.S. sports schedules resume, and midterm elections draw nearer. If crypto market activity also improves, the three main contract types could generate compounding effects. However, as a nascent asset class with less than three years of history, prediction markets still lack sufficient historical data, and the stability of seasonal patterns requires further observation.
Compared to traditional trading and prediction markets, Goldman Sachs takes a more cautious stance on crypto trading.
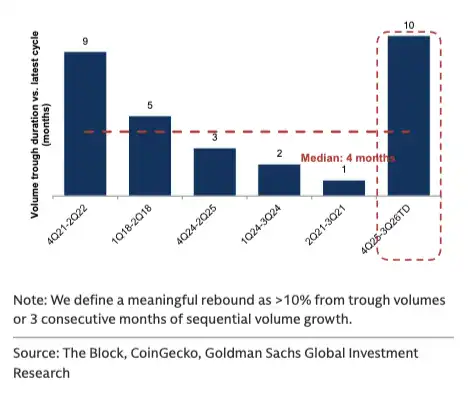
Crypto trading volume in the industry fell 30% MoM in July and another 21% through August—downward trend now sustained for ~10 months, exceeding the median of ~4 months from peak to trough across the past five crypto cycles.
According to the report, in the past six crypto cycles, market cap and trading volume declined on average ~51% and ~66%, respectively. Through the report’s release date, this cycle had seen declines of ~40% and ~75%. This implies that crypto trading contraction has already surpassed historical averages, but neither the magnitude nor duration alone confirms a bottom has been reached.
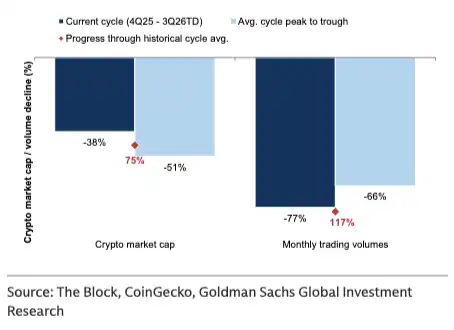
Positive signals emerge from asset prices. One week prior to the report’s release, total crypto market cap rose ~21%. Goldman Sachs believes that if market cap can sustain at current levels, trading volume may recover alongside improving risk appetite.
The key lies in “sustainability.” In April–May this year, crypto market cap briefly surged ~5%, but then reversed, without generating sustained volume rebound. Thus, recent price gains only raise the probability of trading recovery—not enough to signal a trend reversal.
Impacts on brokerages and crypto firms are not uniform. Goldman Sachs statistics show that since 2026, crypto-related stocks’ correlation with total crypto market cap has a median of ~36%. Platforms like Robinhood and Figure, with more diversified businesses, historically exhibit lower correlation with crypto prices; Coinbase’s operating leverage, however, is more directly tied.
Regulation is another variable determining whether crypto markets can transition from cyclical rebounds to structural expansion.
Goldman Sachs sees declining odds of Congress passing the CLARITY Act, a proposed crypto market structure bill, during this term. The Senate failed to vote before its August recess, and midterm elections followed by subsequent congressional breaks have further compressed legislative timelines.
Meanwhile, U.S. regulators continue advancing reforms. The SEC recently proposed a “digital asset innovation exemption,” aiming to provide temporary registration and qualification relief for eligible digital asset issuers and securities. The OCC continues approving digital asset firms for trust bank charters, enabling them to engage in fund transfers and asset custody.
These measures may drive expansion in tokenization, custody, and decentralized finance applications—but Goldman Sachs emphasizes that administrative regulation lacks the durability of congressional legislation. For institutional-scale adoption of digital assets, the market still needs a more stable, clear legal framework.
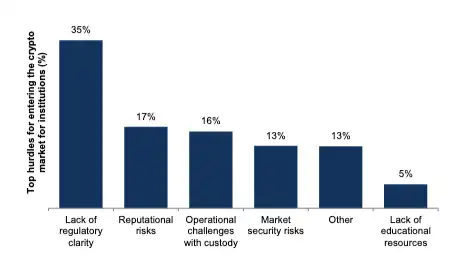
Goldman Sachs’ 2025 institutional survey found that 35% of surveyed managers cited lack of regulatory clarity as the biggest barrier to entering crypto, while 32% listed regulatory clarity as the top catalyst for institutional adoption. Thus, short-term regulatory adjustments can improve market conditions, but congressional legislative progress remains the critical determinant of whether institutional capital can enter systematically.
Against a backdrop of subdued crypto trading, related companies are stabilizing profitability through two primary channels: cost compression and expansion into new businesses with lower correlation to spot trading volume.
Goldman Sachs estimates that five brokerages and crypto firms have implemented cost adjustments as of 2026, cutting annual expenses by ~4% to 5% on average—providing roughly 5.8 percentage points of support to adjusted operating margins. While cost control couldn’t fully offset revenue declines, it mitigated the impact of low trading activity on profits.
On a stock-by-stock basis, Goldman Sachs favors FIGR, HOOD, and IBKR, and views COIN as an upside play upon crypto market recovery.
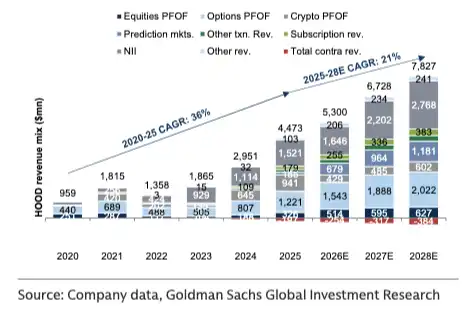
Robinhood’s core thesis rests on account asset growth and business diversification. Goldman Sachs forecasts HOOD’s average revenue per user growing at a CAGR of ~16% from 2025 to 2028, with client assets and revenue rising ~29% and ~21%, respectively. Growth drivers include traditional brokerage, prediction markets, digital banking, credit cards, and wealth management.
Prediction markets are expected to contribute ~13% of HOOD’s revenue in 2026. Its newly launched Rothera prediction market exchange captured ~3% market share within two months of launch. Based on report calculations, this corresponds to ~$150 million in annualized revenue. While prediction market growth is rapid, the platform is still young, and sustainability of current market share remains uncertain.
Figure’s primary growth engine is home equity line of credit (HELOC) lending. Through Q3, its consumer loan market volume continues expanding toward year-over-year growth exceeding 100%. Goldman Sachs attributes the company’s declining composite rates to product mix and channel shifts—not pure price cuts: larger first-lien HELOCs carry lower fees, and FIGR Connect, a capital-light business, has lower fees but higher margins.
Interactive Brokers’ advantage lies in globalization. As of 2026, over 75% of monthly active users and ~85% of app downloads originate outside the U.S. Goldman Sachs forecasts IBKR account growth of 33%, 24%, and 21% in 2026, 2027, and 2028, respectively, with revenue growing at a CAGR of ~15% from 2025 to 2028. Global account growth and pre-tax margins above 75% make it relatively insulated from crypto price volatility.
Coinbase offers more direct exposure to crypto market elasticity. Since Q1 2024, the company has gained ~8 percentage points in crypto derivatives market share; stablecoin, custody, staking, and Prime Brokerage subscription and service businesses contributed ~40% of COIN’s 2025 revenue—relatively decoupled from crypto trading volume.
COIN is also expanding into prediction markets, equities trading, banking, and wealth management. These products currently contribute limited revenue, so Goldman Sachs treats them as potential upside rather than confirmed profit drivers.
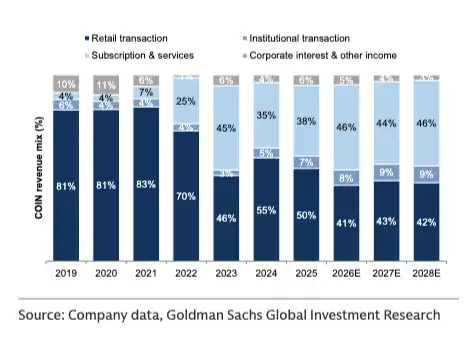
Goldman Sachs’ optimistic outlook on brokerages and crypto stocks rests on several still-uncertain conditions.
First, whether retail equity and options trading volume can overcome summer weakness in September will determine if traditional brokerage seasonal recovery holds. Second, whether sports events and midterm elections can drive prediction market volume spikes will test whether these markets represent sustainable new businesses or merely temporary high-growth categories.
Crypto markets require both price and volume recovery. Sustained high market cap is just the first step; actual rebound in spot and derivatives trading volume will determine whether revenue for related firms truly improves. On the regulatory front, continued easing by administrative agencies can support short-term innovation, but whether Congress can pass a stable market structure law ultimately sets the ceiling for institutional adoption.
Current sector valuations have retreated, but growth quality varies across firms. FIGR, HOOD, and IBKR rely on loans, prediction markets, and global account growth for relatively independent bases; COIN retains higher elasticity to crypto cycles.
Thus, this report does not bet on a renewed crypto bull market. Instead, Goldman Sachs emphasizes that brokerages and crypto platforms are increasingly diversifying revenue sources beyond reliance on single trading cycles. What remains to be validated is whether these new businesses can sustain growth following a seasonal rebound in trading activity.
Original: BlockBeats
Disclaimer: Contains third-party opinions, does not constitute financial advice
Bessent: Advancing the Cryptocurrency Regulatory Framework Through Actions by the SEC and CFTC
2 hours ago
Polymarket US Launches 5-Minute Cryptocurrency Price Movement Prediction Market
2 hours agoCFTC Sues Utah State, Aiming to Block Its Restrictions on Prediction Markets
4 hours agoCancore Closes $7.2 Million Seed Round with Participation from Paper Ventures
6 hours agoNVIDIA and Oracle Expand Collaboration, Scaling NVIDIA Vera Rubin Architecture Deployment to Multi-Gigawatt Levels
7 hours agoCoinbase to List Stable (STABLE)
8 hours agopredict.fun: API documentation site hosted by third-party service provider was attacked, resulting in partial loss of user funds
9 hours ago